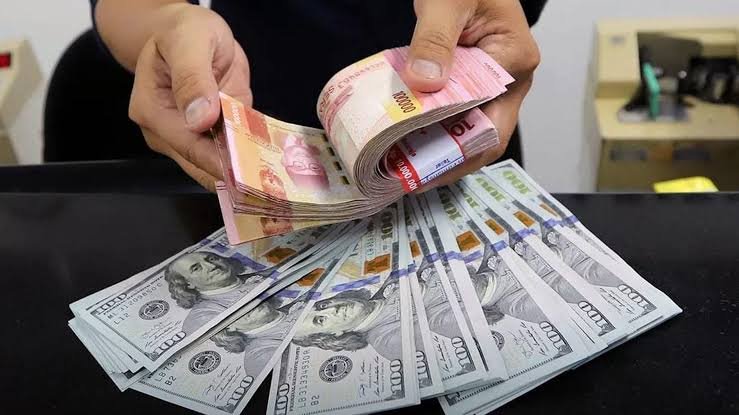
BALINEWSID.COM, DENPASAR — The Indonesian rupiah is approaching Rp18,000 per US dollar as rising global oil prices, higher US Treasury yields, concerns over global inflation and increased foreign-exchange demand from importers put pressure on the currency.
The rupiah’s movement is also drawing attention in Bali, where international tourism generates significant economic activity involving foreign visitors and foreign-exchange transactions. For international tourists carrying US dollars, a weaker rupiah means each dollar can be exchanged for more rupiah.
In Tuesday’s trading session (September 29, 2026), the rupiah weakened by Rp3, or 0.02 percent, to Rp17,981 per US dollar in the spot market. The currency briefly fell to Rp18,036 per dollar before narrowing its losses.
Meanwhile, Bank Indonesia’s Jakarta Interbank Spot Dollar Rate (JISDOR) showed the rupiah strengthening by Rp33, or 0.18 percent, to Rp17,998 per US dollar.
The reference exchange rate therefore remained close to the Rp18,000-per-dollar level.
Erwin Gunawan Hutapea, head of Bank Indonesia’s Monetary and Securities Asset Management Department, said pressure on the rupiah was being driven by growing concerns over global inflation and fiscal risks.
“The depreciation of the exchange rate has been driven by continued concerns over global inflationary pressures and fiscal risks, in line with the increase in oil prices to above US$108 per barrel,” Erwin said.
In addition to higher oil prices, the yield on 10-year US Treasury bonds rose to 5.23 percent, its highest level since 2007.
Higher US Treasury yields can reduce capital flows into emerging markets as dollar-denominated assets become more attractive to investors.
The rupiah has also been affected by capital outflows from emerging-market portfolio assets. Domestically, increased foreign-exchange demand from importers ahead of the end of the third quarter of 2026 has added to pressure on the currency.
On a quarter-to-date basis, the rupiah has weakened by 0.67 percent. Bank Indonesia, however, said the rupiah’s overall movement remained broadly in line with other regional currencies.
Bali Tourism and Foreign-Currency Transactions
The exchange-rate movement has particular relevance for Bali because the province’s tourism economy involves transactions between international visitors and local businesses.
Foreign tourists who exchange US dollars for rupiah receive a larger amount of the local currency when the rupiah weakens. For businesses accepting foreign-currency payments, however, exchange-rate movements also create foreign-exchange management considerations, particularly when their expenses or financial obligations are denominated in different currencies.
The impact of exchange-rate movements on Bali’s tourism sector cannot be determined by the currency alone. Tourist arrivals, length of stay, spending patterns, payment methods and the proportion of transactions conducted in rupiah or foreign currencies are also important factors.
The exchange rate is therefore one of several economic factors that tourism businesses in Bali, including hotels, restaurants, travel agencies, tourism activity providers and retailers serving international visitors, need to monitor.
Bank Indonesia Strengthens Rupiah Stabilization
In response to the pressure, Bank Indonesia has strengthened exchange-rate stabilization measures through various instruments in the foreign-exchange and financial markets without changing its benchmark interest rate.
At its Board of Governors meeting on September 23, 2026, Bank Indonesia kept the BI Rate unchanged at 5.75 percent.
Erwin said the central bank would continue to operate in the market to ensure that market mechanisms function properly and to maintain rupiah stability in line with economic fundamentals.
Intervention has been carried out through non-deliverable forward (NDF) transactions in offshore markets, spot and domestic non-deliverable forward (DNDF) transactions in the domestic market, as well as purchases of government securities, or SBN, in the secondary market.
Bank Indonesia is also strengthening market-based monetary operations while maintaining adequate liquidity in the financial system.
Bank Indonesia Governor Destry Damayanti said the central bank was using non-interest-rate instruments to encourage capital inflows and increase the supply of US dollars in the domestic market.
“We are trying a new, targeted policy. How can we encourage inflows, because this is one of the things needed to increase the supply of US dollars and maintain rupiah stability,” Destry said at a press conference following the September 23 Board of Governors meeting.
Bank Indonesia has provided incentives through reductions in premiums for conventional buy-side hedging swaps with the central bank. The premium reduction is set at 15 percent for three-month tenors, 20 percent for six-month tenors and 25 percent for 12-month tenors.
For DNDF transactions, the premium reduction is set at 25 percent for six-month tenors and 30 percent for 12-month tenors. Bank Indonesia is also continuing incentives for local-currency transactions.
According to Destry, the expanded incentives now cover not only portfolio inflows but also external financing by banks and foreign direct investment (FDI).
Foreign-Exchange Reserves Increase
Despite the pressure on the rupiah, Indonesia’s foreign-exchange reserves continued to increase.
Bank Indonesia reported that foreign-exchange reserves reached US$146.5 billion at the end of August 2026.
The government also recorded cumulative foreign capital inflows into Indonesian government bonds (SBN) and Bank Indonesia Rupiah Securities (SRBI) of Rp140.7 trillion as of September 14, 2026.
Finance Minister Suahasil Nazara said coordination between the government and Bank Indonesia was necessary to maintain macroeconomic stability and investor confidence.
Exchange-rate pressures remain a concern because a weaker rupiah can raise the cost of imported goods and, in turn, add pressure to domestic inflation.
M. Rizal Taufikurahman, head of the Macroeconomics and Finance Center at the Institute for Development of Economics and Finance (Indef), said Bank Indonesia did not necessarily have to mechanically follow interest-rate moves by major global central banks as long as domestic inflation remained under control and the rupiah could still be stabilized.
However, Rizal said increasingly aggressive global monetary tightening could put additional pressure on the exchange rate and capital flows.
“An increase in the BI Rate could become an option when exchange-rate pressure becomes persistent and begins to spill over into inflation and market expectations,” he said.
Trioksa Siahaan, head of research at the Indonesian Banking Development Institute (LPPI), said Bank Indonesia needed strategies beyond the BI Rate to maintain rupiah stability.
One such measure, he said, was ensuring that domestic demand for US dollars was supported by clear underlying transactions.
Discussion (0)
No comments yet.